Disability Insurance for Residents of NJ, NY, CT, PA and Beyond
Disability insurance provides added financial security by paying an insured person an income when that person is unable to work because of an accident or illness. It is not surprising that disability insurance is critical. Consider that at age 40, the average worker faces only a 14-percent chance of dying before age 65. That same worker, however, faces a 21-percent chance of being disabled for 90 days or more.
There are three basic ways to replace income:
Employer-paid disability insurance
This is required in most states. Most employers provide some short-term sick leave. Many larger employers provide long-term disability coverage as well, typically with benefits of up to 60 percent of salary lasting from five years to age 65 and in some cases extended for life.
Social Security disability benefits
This can be paid to workers whose disability is expected to last at least 12 months and is so severe that no gainful employment can be performed.
Individual disability income insurance policies
Other limited replacement income is available for workers under some circumstances from workers compensation (if the injury or illness is job-related), auto insurance (if disability results from an auto accident) and the Department of Veterans Affairs.
For most workers, even those with some employer-paid coverage, an individual disability income policy is the best way to ensure adequate income in the event of disability. When you buy a private disability income policy, you can expect to replace from 50% to 70% of income.
| Employer-paid disability insurance | This is required in most states. Most employers provide some short-term sick leave. Many larger employers provide long-term disability coverage as well, typically with benefits of up to 60 percent of salary lasting from five years to age 65 and in some cases extended for life. |
| Social Security disability benefits | This can be paid to workers whose disability is expected to last at least 12 months and is so severe that no gainful employment can be performed. |
| Individual disability income insurance policies | Other limited replacement income is available for workers under some circumstances from workers compensation (if the injury or illness is job-related), auto insurance (if disability results from an auto accident) and the Department of Veterans Affairs. For most workers, even those with some employer-paid coverage, an individual disability income policy is the best way to ensure adequate income in the event of disability. When you buy a private disability income policy, you can expect to replace from 50% to 70% of income. |
There are other things to consider as well when looking into disability insurance. These include:
- Short-Term vs Long-Term Policies
- Noncancelable & Guaranteed Provisions
- Additional Purchase Options
- Coordination of Benefits
- Cost of Living Adjustments
- Residual or Partial Disability Rider
- Return of Premium Provisions
- Waiver of Premium Provisions
Want to get the straight word on disability insurance?
Contact Muller Insurance to learn more about coverage throughout New Jersey, New York, Connecticut, Pennsylvania, Nevada, and other states. We are here to help.
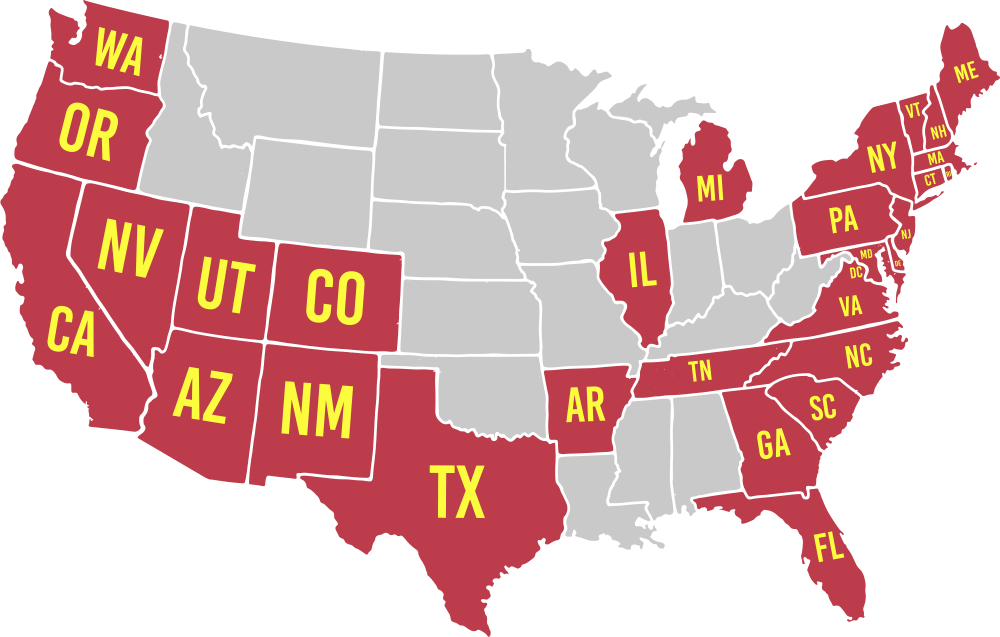
Licensed in 29 States
One Trusted Agency
Additional Resources

Stay Insured When You Rent or Hire a Vehicle
People may put a significant amount of effort into adequately insuring their personal vehicles, but they frequently make quick assumptions about coverage of rented or hired vehicles. However, it is

If a Tree Falls…
You know the conundrum about trees falling in the forest. Have you heard the one about trees falling on the house? No doubt, that falling tree will be heard and

How Rental Property Insurance Differs from Other Insurance
Although rental property insurance shares similarities with other forms of insurance, there are some protections you will only receive with a rental property policy. Landlords need to know what makes